
Covers T.R. Jain & V.K. Ohri (2026-27) ch 10. Based on NCERT Introductory Macroeconomics, Chapter 5 (Reprint 2026-27) and the CBSE curriculum 2026-27.
- What a government budget is, its two parts (revenue budget and capital budget) and its three objectives
- Why public goods have to be provided by the government
- How to sort every receipt and every expenditure into revenue or capital, with the reason
- How to work out the revenue, fiscal and primary deficit from data, step by step, and what each one means
- The government expenditure, tax, transfer and balanced budget multipliers; proportional taxes; government debt, FRBMA and GST
1 Government Budget: Meaning and Its Components
An economy in which there is both a private sector and the government is a mixed economy. The government influences economic life in many ways; this chapter looks only at the functions carried out through the government budget.
1.1 Meaning of the budget
The government budget is a statement of the estimated receipts and estimated expenditure of the government for a financial year (1 April to 31 March). Under Article 112 of the Constitution, the government must present it before Parliament. This ‘Annual Financial Statement’ is the main budget document of the government.
- The budget is for one year, but its impact is felt in the years that follow
- So the budget keeps two accounts: items relating to the current financial year only go into the revenue account (revenue budget); items that concern the assets and liabilities of the government go into the capital account (capital budget)
- A Finance Bill is presented along with the Annual Financial Statement; it details the imposition, abolition, remission, alteration or regulation of the taxes proposed in the budget
- Since Independence, with the Five-Year Plans, the budget is not merely a statement of receipts and expenditure; it has become a significant national policy statement
The revenue budget contains the government’s revenue receipts and revenue expenditure, the items that relate to the current financial year only. The capital budget contains capital receipts and capital expenditure, the items that change the government’s assets and liabilities.
1.2 Components of the government budget
The book’s Chart 1 (The Components of the Government Budget) shows this classification.
2 Objectives of the Government Budget
The government plays a very important role in increasing the welfare of the people. To do this it intervenes through the budget in three ways: allocation, redistribution and stabilisation. All three operate through the expenditure and receipts of the government.
2.1 Allocation function and public goods
Allocation function: the government provides certain goods and services which cannot be provided by the market mechanism (exchange between individual consumers and producers), such as national defence, roads and government administration. These are called public goods.
To see why the government must provide public goods, compare them with private goods (clothes, cars, food items). There are two major differences:
| Basis | Private goods | Public goods |
|---|---|---|
| 1. Rivalry | One person’s consumption reduces what is available to others (rival relationship). The chocolate I eat is not available to anyone else | One person’s consumption does not reduce the amount available to others (non-rivalrous). A public park or measures to reduce air pollution benefit everyone |
| 2. Exclusion | Anyone who does not pay can be excluded. No ticket, no movie | There is no feasible way of excluding anyone from the benefits, so they are non-excludable |
| Examples | Clothes, cars, food items | National defence, roads, government administration, a public park |
Free-riders are non-paying users who enjoy the benefits of a public good. It is difficult and sometimes impossible to collect fees for a public good.
Public provision
- The good is financed through the budget
- It can be used without any direct payment
- It may be produced by the government or the private sector
Public production
- The good is produced directly by the government
- Only one way of providing it publicly
- Not every public good is produced by the government
For “Why must public goods be provided by the government?” (Exercise 1), write all four points: non-rivalrous, non-excludable, the free-rider problem, and “the link through payment is broken”.
2.2 Redistribution function
- National income goes either to the private sector (firms and households), called private income, or to the government, called public income
- Out of private income, what finally reaches households is personal income; the amount that can be spent is personal disposable income
- The government affects households’ disposable income by making transfers and collecting taxes
Redistribution function: changing households’ personal disposable income through taxes and transfers so as to bring about a distribution of income that society considers ‘fair’.
Example: higher income tax rates on the rich (progressive tax) and pensions, scholarships or cheap food grain for the poor. The redistribution objective is sought to be achieved mainly through progressive income taxation (section 3.1).
2.3 Stabilisation function
- The level of employment and prices depends on aggregate demand, which depends on the spending decisions of millions of private agents apart from the government
- If demand is too low, labour and other resources are not fully used; since wages and prices do not fall below a level, employment does not return to its earlier level automatically. The government must raise aggregate demand
- If demand exceeds available output under high employment, inflation may result. The government must use restrictive measures to reduce demand
Stabilisation function: the intervention of the government, whether to expand demand or reduce it, to correct fluctuations in income and employment.
To identify the objective behind a policy, ask: is it providing a good or service (allocation), changing whose income (rich to poor: redistribution), or managing total demand and prices (fighting recession or inflation: stabilisation)? Lower taxes for the poor and higher taxes for the rich is redistribution; building a road is allocation.
3 Classification of Receipts
Every receipt falls into one of two classes. The test: does the receipt create a liability for the government (an obligation to repay), or reduce its financial assets? If yes, it is a capital receipt; if neither, it is a revenue receipt.
3.1 Revenue receipts
Revenue receipts are receipts that do not lead to a claim on the government (they need not be repaid). They are therefore termed non-redeemable. They are divided into tax revenue and non-tax revenue.
(a) Tax revenue
| Basis | Direct taxes | Indirect taxes |
|---|---|---|
| On what | Income of individuals (personal income tax) and profits of firms (corporation tax) | Goods and services |
| Book’s examples | Personal income tax, corporation tax; wealth tax, gift tax, estate duty (now abolished) | Excise taxes (on goods produced within the country), customs duties (on imports and exports), service tax; now GST |
- Paper taxes: wealth tax, gift tax and estate duty never brought in a large amount of revenue, so they are called ‘paper taxes’
- Progressive income taxation: the higher the income, the higher the tax rate. This is how the redistribution objective is pursued
- Firms are taxed on a proportional basis: the tax rate is a particular proportion of profits
- Excise rates: necessities exempted or taxed at low rates; comforts and semi-luxuries moderately taxed; luxuries, tobacco and petroleum products taxed heavily
- GST (Goods and Services Tax) brought a dramatic change in India’s tax system; it covers both goods and services and was implemented by the Centre, 28 states and 7 Union territories from 1 July 2017 (details in section 11)
(b) Non-tax revenue
- Interest receipts on loans given by the central government
- Dividends and profits on investments made by the government
- Fees and other receipts for services rendered by the government
- Cash grants-in-aid from foreign countries and international organisations
3.2 Capital receipts
Capital receipts are all those receipts of the government which create a liability or reduce financial assets, such as fresh loans and the sale of government assets (shares in Public Sector Undertakings).
Disinvestment: the sale of the government’s shares in Public Sector Undertakings (PSUs). It reduces the government’s financial assets, so it is a capital receipt.
- A loan must be repaid with interest in future, so it creates a liability
- When an asset is sold, the earnings from that asset in future disappear
- So capital receipts can be debt creating (borrowing, such as market loans) or non-debt creating (recovery of loans, disinvestment)
Non-debt creating capital receipts are capital receipts which are not borrowings and therefore do not give rise to debt. The book’s examples: recovery of loans and the proceeds from the sale of PSUs.
| Receipt | Class | Reason |
|---|---|---|
| Income tax, corporation tax, GST, customs duty | Revenue (tax) | No liability, no reduction in assets |
| Interest on government loans, dividends from PSUs, fees | Revenue (non-tax) | No liability, no reduction in assets |
| Cash grants from abroad | Revenue (non-tax) | Need not be repaid |
| Market borrowing, borrowing from RBI, external loans | Capital (debt creating) | Creates a liability |
| Recovery of loans given to states | Capital (non-debt) | Reduces a financial asset (the loan given) |
| PSU disinvestment | Capital (non-debt) | Reduces a financial asset (shares) |
1. Interest received on a loan is a revenue receipt, but recovery of the loan (principal coming back) is a capital receipt.
2. Disinvestment creates no liability, yet it is a capital receipt because assets fall.
3. Non-debt creating capital receipts do not add to debt, so they are added to receipts when working out the fiscal deficit.
4 Classification of Expenditure
4.1 Revenue expenditure
Revenue expenditure is expenditure incurred for purposes other than the creation of physical or financial assets of the central government. It covers the normal functioning of government departments and various services, interest payments on debt, and grants given to state governments and other parties (even though some grants may be meant for creating assets).
- Budget documents classify total expenditure into plan and non-plan expenditure (item 7 of Table 5.1)
- Plan revenue expenditure: central Plans (the Five-Year Plans) and central assistance for State and Union Territory plans
- Non-plan expenditure, the more important component of revenue expenditure, covers general, economic and social services; main items: interest payments, defence services, subsidies, salaries and pensions
- Interest payments on market loans, external loans and reserve funds are the single largest component of non-plan revenue expenditure
- Defence expenditure is committed expenditure: given national security concerns, there is little scope for drastic reduction
- A footnote in the book records the case against the plan/non-plan classification: it encouraged starting new schemes while neglecting maintenance of existing capacity, and created the misperception that non-plan expenditure is wasteful, hurting allocations to education and health, where salaries are an important element
Subsidies are a policy instrument aimed at increasing welfare. The government gives implicit subsidies by under-pricing public goods and services like education and health, and explicit subsidies on items such as exports, interest on loans, food and fertilisers.
| Year | 2014-15 | 2015-16 | 2018-19 | 2020-21 | 2022-23 (B.E.) |
|---|---|---|---|---|---|
| Subsidies, % of GDP | 2.02 | 1.8 | 1 | 3.6 | 1.2 |
4.2 Capital expenditure
Capital expenditure is expenditure of the government which results in the creation of physical or financial assets or a reduction in financial liabilities: acquisition of land, buildings, machinery, equipment, investment in shares, and loans and advances by the central government to state and union territory governments, PSUs and other parties.
- Capital expenditure is also categorised as plan and non-plan in the budget documents
- Plan capital expenditure: like its revenue counterpart, the central plan and central assistance for state and union territory plans
- Non-plan capital expenditure: various general, social and economic services provided by the government
| Basis | Revenue expenditure | Capital expenditure |
|---|---|---|
| Assets | No asset is created | Physical or financial asset is created |
| Liabilities | No reduction in liabilities | Can reduce liabilities (repaying the principal of a loan) |
| Nature | Normal, current running of the government; recurring | Investment in nature; adds to future capacity |
| Examples | Salaries, pensions, interest, subsidies, grants to states, defence services | Roads and buildings, machinery, purchase of shares, loans to states, repayment of loan principal |
1. Interest payment is revenue expenditure, but repayment of loan principal is capital expenditure (a liability falls).
2. A grant to states is revenue expenditure even if the state builds an asset with it; a loan to states is capital expenditure.
3. A large amount or “public benefit” does not make spending capital; the test is asset creation or a reduction in liabilities.
4.3 Three policy statements with the budget (FRBMA, 2003)
The Fiscal Responsibility and Budget Management Act, 2003 (FRBMA) mandates three policy statements along with the budget:
| Statement | What it does |
|---|---|
| Medium-term Fiscal Policy Statement | Sets a three-year rolling target for specific fiscal indicators; examines whether revenue expenditure can be financed through revenue receipts on a sustainable basis and how productively capital receipts, including market borrowings, are being used |
| Fiscal Policy Strategy Statement | Sets the government’s priorities in the fiscal area, examining current policies and justifying any deviation in important fiscal measures |
| Macroeconomic Framework Statement | Assesses the prospects of the economy with respect to the GDP growth rate, the fiscal balance of the central government and the external balance |
Gender budgeting: the 2005-06 Indian Budget introduced a statement highlighting the gender sensitivities of budgetary allocations, and the 2006-07 budget enlarged it. It covers special initiatives for empowering women, the use of resources allocated for women, and the impact of public expenditure and policies on women.
5 Balanced, Surplus and Deficit Budget
Budget deficit: when the government spends more than it collects. Formally, it is the excess of total expenditure (revenue and capital) over total receipts (revenue and capital). From the 1997-98 budget, the practice of showing the budget deficit was discontinued in India.
6 Measures of Government Deficit
There are three measures of deficit, and each has its own meaning for the economy. First look at the book’s table, then each measure.
| Table 5.1: Receipts and Expenditures of the Central Government, 2024-25 (P.A.), % of GDP | |
|---|---|
| 1. Revenue receipts (a + b) | 9.2 |
| (a) Tax revenue (net of states’ share) | 7.9 |
| (b) Non-tax revenue | 1.4 |
| 2. Revenue expenditure, of which | 11.8 |
| (a) Interest payments | 3.6 |
| (b) Major subsidies | 1.4 |
| (c) Defence expenditure | 1.0 |
| 3. Revenue deficit (2 − 1) | 2.6 |
| 4. Capital receipts (a + b + c), of which | 5.8 |
| (a) Recovery of loans | 0.1 |
| (b) Other receipts (mainly PSU disinvestment) | 0.1 |
| (c) Borrowings and other liabilities | 5.6 |
| 5. Capital expenditure | 3.2 |
| 6. Non-debt receipts [1 + 4(a) + 4(b)] | 9.4 |
| 7. Total expenditure [2 + 5] | 15.0 |
| 8. Fiscal deficit [7 − 1 − 4(a) − 4(b)] | 5.6 |
| 9. Primary deficit [8 − 2(a)] | 2.0 |
Source: Economic Survey 2024-25, Statistical Appendix (as given in the book). Total expenditure is 11.8 + 3.2 = 15.0. The book shows “–” against plan and non-plan expenditure. Tax plus non-tax revenue (7.9 + 1.4) differs slightly from 9.2 because of rounding.
6.1 Revenue deficit
The revenue deficit refers to the excess of the government’s revenue expenditure over revenue receipts. It includes only those transactions that affect the current income and expenditure of the government.
What a revenue deficit means:
6.2 Fiscal deficit
The fiscal deficit is the difference between the government’s total expenditure and its total receipts excluding borrowing. It has to be financed through borrowing, so it indicates the total borrowing requirement of the government from all sources.
- Net borrowing at home includes borrowing directly from the public through debt instruments (for example, the various small savings schemes) and indirectly from commercial banks through the Statutory Liquidity Ratio (SLR)
- The gross fiscal deficit is a key variable in judging the financial health of the public sector and the stability of the economy
- The relation above shows that the revenue deficit is a part of the fiscal deficit
- In Table 5.1, 9.4 is the total of non-debt receipts (item 6); the non-debt creating capital receipts within it are 0.1 + 0.1 = 0.2
- A large share of revenue deficit in the fiscal deficit shows that a large part of borrowing is being used for consumption rather than investment; the book’s summary says that its growth points to a deterioration in the quality of government expenditure, with lower capital formation
6.3 Primary deficit
The primary deficit is the fiscal deficit minus net interest liabilities. The borrowing requirement includes interest on accumulated debt; the primary deficit removes it to focus on present fiscal imbalances.

Revenue deficit: how much consumption the government is financing by borrowing. Fiscal deficit: how much the government must borrow in all. Primary deficit: borrowing needed because of this year’s policies, leaving out interest on past debt. If the primary deficit is zero, the government is borrowing only to pay interest.
6.4 Solved numericals
Given (₹ crore)
Tax revenue 800; non-tax revenue 150; revenue expenditure 1,200 (of which interest payments 300); capital expenditure 400; recovery of loans 30; disinvestment 20; borrowings 600
Find
Revenue deficit, fiscal deficit, primary deficit; share of revenue deficit in fiscal deficit
Step 1: Revenue receipts = tax + non-tax = 800 + 150 = ₹950 crore (½)
Formula: Revenue deficit = Revenue expenditure − Revenue receipts (½)
Substitution: 1,200 − 950 = ₹250 crore (1)
Step 2: Total expenditure = 1,200 + 400 = ₹1,600 crore; non-debt capital receipts = 30 + 20 = ₹50 crore (½)
Formula: Fiscal deficit = Total expenditure − (Revenue receipts + Non-debt capital receipts) (½)
Substitution: 1,600 − (950 + 50) = ₹600 crore (1)
Check: equals borrowings of 600; and RD + capex − non-debt receipts = 250 + 400 − 50 = 600
Step 3: Primary deficit = Fiscal deficit − Interest payments = 600 − 300 = ₹300 crore (1)
Share: 250 ÷ 600 × 100 ≈ 41.7%
Interpretation: about 41.7% of all government borrowing goes into consumption (revenue) spending, not investment; half of the borrowing (300) is to pay interest on past debt.
Given (₹ crore)
Fiscal deficit 4,000; total expenditure 15,000; non-tax revenue 1,500; non-debt creating capital receipts 500
Find
Tax revenue
Formula: Fiscal deficit = Total expenditure − (Tax revenue + Non-tax revenue + Non-debt capital receipts) (½)
Substitution: 4,000 = 15,000 − (Tax revenue + 1,500 + 500) (½)
Tax revenue = 15,000 − 4,000 − 2,000 = ₹9,000 crore (1)
Interpretation: remove borrowing (4,000) and the other non-debt receipts (2,000) from total expenditure; what remains came from taxes.
1. Do not add borrowing to receipts for the fiscal deficit; total receipts including borrowing always equal total expenditure, so the deficit would come out as zero.
2. Remember to subtract non-debt capital receipts (recovery of loans, disinvestment); forgetting them gives 650 in Example 1 instead of 600.
3. For the primary deficit, interest is subtracted, not added (300, not 900, in Example 1).
4. The revenue deficit uses revenue items only; subtracting capital receipts too (1,200 − 1,000 = 200) is wrong.
7 Fiscal Policy and the Multipliers (Not in CBSE 2026-27 syllabus)
This is Box 5.1 of the book. The CBSE 2026-27 curriculum does not list it, but Exercises 5 to 10 are based on it and the UP, Bihar, Rajasthan and MP boards teach from this book. The multiplier of Chapter 4 is extended here to include the government.
Fiscal policy: the use of changes in government expenditure and taxes to stabilise the level of output and employment. This was one of Keynes’s main ideas in The General Theory of Employment, Interest and Money.
7.1 Aggregate demand with the government
- The government affects equilibrium income in two specific ways: government purchases (G) increase aggregate demand, and taxes and transfers change the relation between income (Y) and disposable income (YD)
- Lump-sum taxes (T): taxes that do not depend on income; the government makes a constant amount of transfers (T̄R)
- Taxes lower disposable income and consumption: someone who earns ₹1 lakh and pays ₹10,000 in taxes has the same disposable income as someone who earns ₹90,000 and pays no taxes
disposable income = Y − T + TR
autonomous consumption
A lump-sum tax shifts the consumption schedule down in a parallel way, and so the AD curve shifts down in parallel too.
7.2 Changes in government expenditure
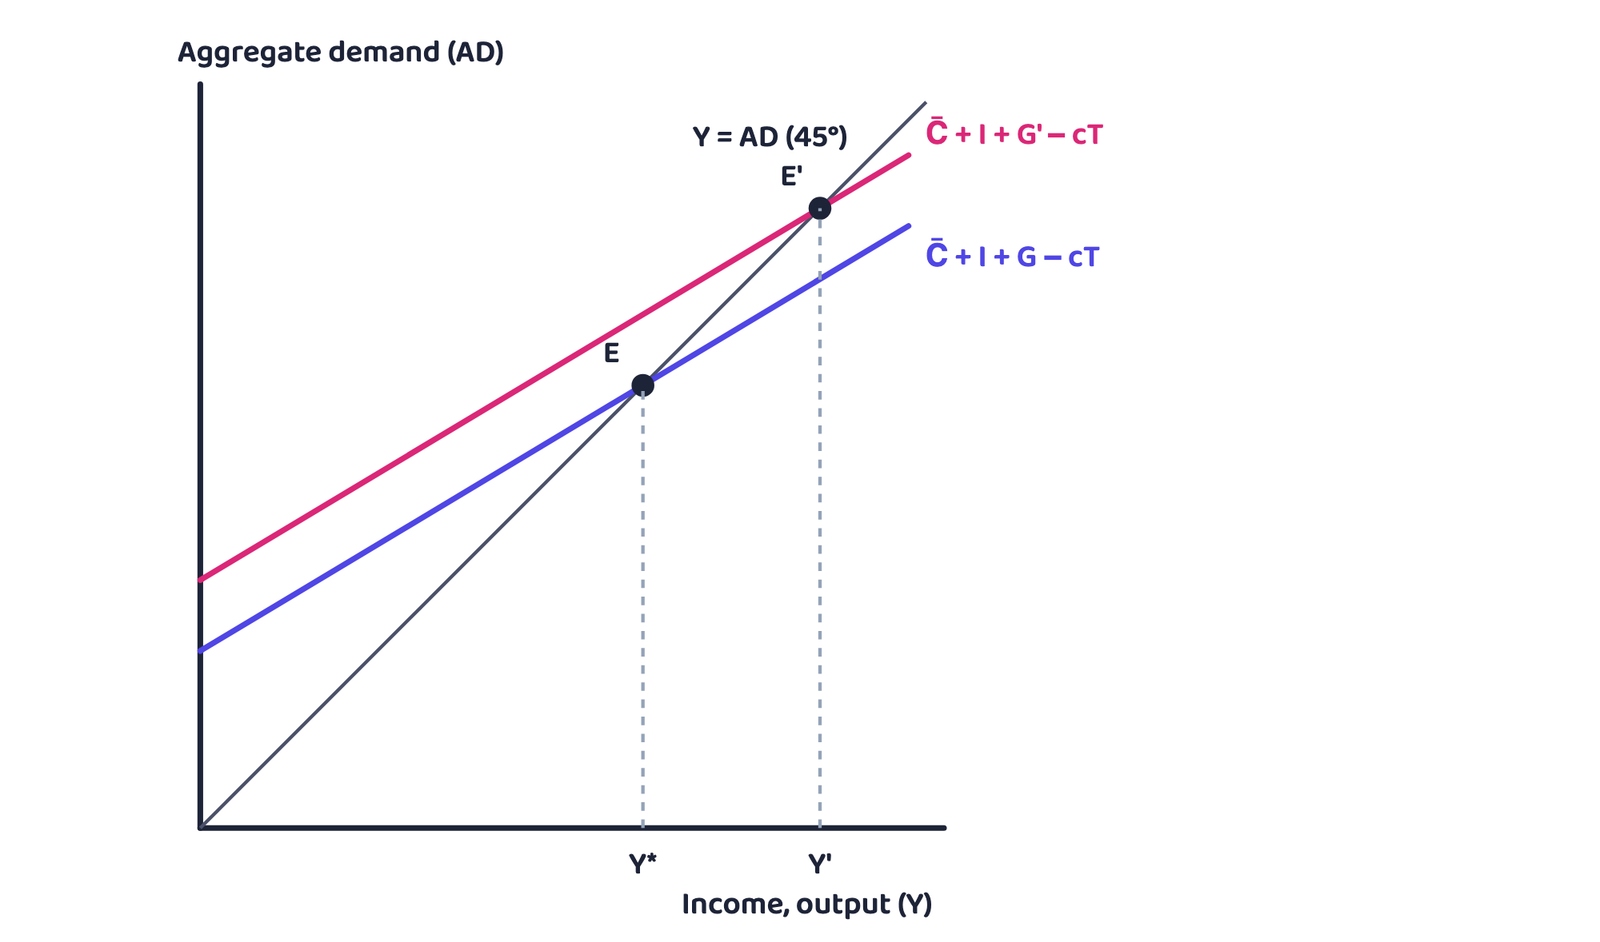
- Raise G keeping taxes constant: when G exceeds T, the government runs a deficit
- G is a component of aggregate spending, so the AD schedule shifts up to AD′
- At the initial output, demand exceeds supply, firms expand production, and the new equilibrium is at E′; the multiplier mechanism (Chapter 4) is at work
7.3 Changes in taxes: the tax multiplier
- A tax cut raises disposable income (Y − T) at each level of income
- The AD schedule shifts up, but only by a fraction c of the tax cut (part of the cut is saved)

- The tax multiplier is negative: a tax cut raises consumption and output; a tax increase reduces them
- In absolute value the tax multiplier is smaller than the government spending multiplier: government spending directly affects total spending, while taxes enter only through their effect on disposable income and hence consumption; a tax cut of ΔT raises spending by only cΔT in the first round
- For any value of the MPC, the tax multiplier is always one less in absolute value than the government expenditure multiplier
Given (the book’s Example 5.1)
MPC c = 0.8; G rises by 100; taxes are cut by 100
Find
Both multipliers and the change in income
Government expenditure multiplier: ; ΔY = 5 × 100 = 500
Tax multiplier: ; ΔT = −100, so ΔY = −4 × (−100) = 400
Interpretation: a tax cut of the same amount raises income by less than a rise in G (400 < 500).
7.4 Balanced budget multiplier
Balanced budget multiplier: if an increase in government spending is matched by an equal increase in taxes (ΔG = ΔT, budget stays balanced), output rises by exactly the increase in government spending. This multiplier is unity (1).
In Example 5.1, a rise in G of 100 raises output by 500 and a tax rise of 100 reduces income by 400; the net rise is 100, exactly ΔG. Equilibrium income is the final income reached after all the rounds of the multiplier have worked themselves out.
7.5 Proportional taxes
- A more realistic assumption: the government collects a constant fraction t of income as taxes, T = tY
- Consumption function:
- Proportional taxes lower consumption at each level of income and also lower the slope of the consumption function: the MPC out of income falls from c to c(1 − t)
- So the new AD schedule is flatter (Figure 4)

Given (the book’s Example 5.2)
c = 0.8, tax rate t = 0.25, G rises by 100
Find
The multiplier and the change in income
Step 1: c(1 − t) = 0.8 × 0.75 = 0.60; consumption now rises by 0.60, not 0.80, for every unit rise in income
Formula:
Substitution: ΔY = 2.5 × 100 = 250
Interpretation: compared with lump-sum taxes (multiplier 5, rise 500), both the multiplier and the rise in income are smaller.
Given
C = 40 + 0.75YD, T = 0.2Y, I = 60, G = 100, no transfers
Find
Equilibrium income; is the budget balanced?
Formula: (½)
Substitution: Y* = (40 + 60 + 100) ÷ (1 − 0.75 × 0.8) = 200 ÷ 0.4 (½)
Result: Y* = 500 (1)
Tax revenue: 0.2 × 500 = 100 = G, so the budget is balanced.
A cut in the tax rate works like a rise in the propensity to consume: AD swings up to AD′, demand exceeds output at the initial income, and the new higher income is Y′.

7.6 Automatic stabilisers and discretionary fiscal policy
Automatic (built-in) stabiliser: a feature of the economy that reduces fluctuations automatically, without any decision-maker taking action, such as the proportional income tax and welfare transfers. The proportional income tax acts as a shock absorber because it makes disposable income, and so consumer spending, less sensitive to fluctuations in GDP.
In a boom
- GDP rises, but disposable income rises by less, because a part is siphoned off as taxes
- The upward swing in consumption is limited
- Tax receipts rise and press on high consumption spending
In a recession
- GDP falls, but disposable income falls less sharply
- Consumption does not drop as much as it would with a fixed tax liability
- Welfare payments help sustain consumption
- The private sector has built-in stabilisers too: corporations maintain their dividends in the face of a change in income in the short run, and households try to maintain their previous living standards
- Built-in stabilisers reduce only part of the fluctuation; the rest must be taken care of by deliberate policy
Discretionary fiscal policy: deliberate action by the government to stabilise the economy. For example, if investment falls from I0 to I1, government spending is raised from G0 to G1 so that autonomous expenditure (C̄ + I0 + G0 = C̄ + I1 + G1) and equilibrium income stay the same.
7.7 Changes in transfers
- If the government raises transfers T̄R instead of purchases, autonomous spending rises only by cΔT̄R
- Part of any increase in transfers is saved, so output rises by less than with an equal rise in G
Given (the book’s Example 5.3)
c = 0.75, lump-sum taxes; government purchases rise by 20; transfers rise by 20
Find
The change in equilibrium income in each case
G up by 20: 80
Transfers up by 20: 60
Interpretation: income rises by less with transfers than with an equal rise in government purchases (60 < 80).

Given
C = 50 + 0.8YD, I = 100, G = 70, lump-sum tax T = 50, no transfers
Find
Equilibrium income; the budget position
Formula: (½)
Substitution: Y* = (50 − 0.8 × 50 + 100 + 70) ÷ 0.2 = 180 ÷ 0.2 (½)
Result: Y* = 900 (1)
Check: YD = 900 − 50 = 850; C = 50 + 0.8 × 850 = 730; AD = 730 + 100 + 70 = 900 = Y
Budget: G = 70 > T = 50, so a deficit budget of 20.
1. The tax multiplier is negative: write ΔY as negative when taxes rise.
2. If consumption depends on YD, subtract taxes from Y: C = C̄ + c(Y − T + TR).
3. With proportional taxes the multiplier is 1/(1 − c(1 − t)), not 1/(1 − c).
4. The balanced budget multiplier is 1 for every MPC; add the G and tax multipliers, do not subtract them.
5. The transfer multiplier is c/(1 − c), smaller than the G multiplier.
8 Government Debt (Not in CBSE 2026-27 syllabus)
- Budgetary deficits must be financed by taxation, borrowing or printing money; governments have mostly relied on borrowing, giving rise to government debt
- Deficits are a flow which add to the stock of debt
- Borrowing year after year accumulates debt, more interest must be paid, and the interest payments themselves add to the debt
8.1 Is government debt a burden?
What is true of one small trader’s debt may not be true of the government’s debt: the ‘whole’ must be dealt with differently from the ‘part’, because the government can raise resources through taxation and printing money.
| Arguments that debt is a burden | Arguments that it is not |
|---|---|
| The government borrows today by issuing bonds and may repay some twenty years later by raising taxes on the young who have just entered the workforce; their disposable income and consumption fall, so national savings fall | Ricardian equivalence: forward-looking consumers see that borrowing today means higher taxes later; caring for their children, they save more now, fully offsetting government dissaving, so national savings do not change |
| Government borrowing reduces the savings available to the private sector; if this reduces capital formation and growth, debt is a ‘burden’ on future generations | ‘Debt does not matter because we owe it to ourselves’: resources move between generations, but purchasing power stays within the nation |
| Debt owed to foreigners is a burden, since goods must be sent abroad to match the interest payments | If the government invests in infrastructure and the return is greater than the rate of interest, future generations may be better off; the debt could be paid off by the growth in output |
Ricardian equivalence: the view that taxation and borrowing are equivalent means of financing expenditure. Spending financed by borrowing today, to be repaid by taxes in future, has the same effect on the economy as spending financed by a tax increase today. It is named after the nineteenth century economist David Ricardo, who first argued that in the face of high deficits people save more.
The traditional argument is that when the government cuts taxes and runs a deficit, consumers spend more of their after-tax income; they may be short-sighted, or may expect the future taxes to fall on future generations. The book’s conclusion (Summary 6): public debt is burdensome if it reduces future growth in output.
8.2 Other perspectives on deficits and debt
- Are deficits inflationary? The criticism: higher spending or tax cuts raise aggregate demand; if firms cannot produce more at ongoing prices, prices rise. But if there are unutilised resources, output is held back by lack of demand; a high fiscal deficit then brings higher demand and greater output, and need not be inflationary
- Crowding out: if the government borrows by issuing bonds, these compete with corporate bonds for the available savings; some private borrowers get ‘crowded out’ of financial markets. But the flow of savings is fixed only if income cannot rise; if deficits raise production, income and saving both rise, and both government and industry can borrow more
- The growth in debt should be judged by the growth of the economy as a whole (see the infrastructure argument in the table above)
9 Deficit Reduction (Not in CBSE 2026-27 syllabus)
Raising receipts
- Increase taxes; the government has been trying to raise tax revenue with greater reliance on direct taxes (the book says indirect taxes are regressive, impacting all income groups equally)
- Sale of shares in PSUs
Cutting expenditure (main thrust)
- Make government activities more efficient through better planning and administration
- Withdraw from some areas (change the scope of government)
- But cuts in agriculture, education, health and poverty alleviation would hurt the economy
- A Planning Commission study (Programme Evaluation Organisation) estimated that to transfer Re 1 to the poor, the government spends ₹3.65 as food subsidy; the book takes this as showing that cash transfers would increase welfare
- Many countries with huge deficits put in place self-imposed limits on expenditure (in India, the FRBMA)
- A larger deficit does not always mean a more expansionary policy: in a recession GDP falls and firms and households pay less tax, so the deficit rises in a recession and falls in a boom even with no change in policy
10 Fiscal Responsibility and Budget Management Act, 2003 (Not in CBSE 2026-27 syllabus)
In a multi-party parliamentary system, electoral concerns play an important role in expenditure policy. A legal provision applicable to all governments, present and future, is argued to be effective in keeping deficits under control.
| # | Main features of the FRBMA |
|---|---|
| 1 | Reduce the fiscal deficit to not more than 3% of GDP and eliminate the revenue deficit by March 31, 2009, then build up an adequate revenue surplus |
| 2 | Reduce the fiscal deficit by 0.3% of GDP each year and the revenue deficit by 0.5%; if tax revenue falls short, cut expenditure |
| 3 | Actual deficits may exceed targets only on grounds of national security, natural calamity or other exceptional grounds the central government specifies |
| 4 | The central government shall not borrow from the RBI except by way of advances to meet temporary excess of cash disbursements over cash receipts |
| 5 | The RBI must not subscribe to primary issues of central government securities from 2006-07 |
| 6 | Measures for greater transparency in fiscal operations |
| 7 | Three statements laid before both Houses with the Annual Financial Statement (section 4.3) |
| 8 | Quarterly review of trends in receipts and expenditure placed before both Houses |
- The Act applies to the central government; 26 states have enacted their own fiscal responsibility laws
- Concern: welfare expenditure may be reduced to meet the targets
- FRBM Review Committee: given the task of keeping the 2003 framework while revamping it for India’s changed situation and future growth path
11 Goods and Services Tax (GST): One Nation, One Tax, One Market
This is Box 5.3 of the book; Exercise 15 is based on it. The CBSE 2026-27 curriculum lists the “concept of GST” with Indian Economic Development, Chapter 3.
The Goods and Services Tax (GST), operational from 1 July 2017, is the single comprehensive indirect tax on the supply of goods and services, from the manufacturer or service provider to the consumer. It is a destination-based consumption tax with the facility of Input Tax Credit (ITC) in the supply chain, with one rate for one type of good or service across the country.
Pre-GST system
- Tax at each stage on the total value of the good, with minimal input tax credit
- The total value included taxes already paid on intermediate goods: tax on tax, or cascading
- Many Central and State taxes and cesses
GST
- Tax at every stage of supply, with credit for the tax paid at the previous stage
- Effectively a tax on value addition at each stage
- Laws, procedures and rates standardised across the country; a common market
| Central taxes subsumed in GST | State taxes subsumed in GST |
|---|---|
| Central Excise Duty, Service Tax, Central Sales Tax, cesses like KKC and SBC | VAT/Sales Tax, Entry Tax, Luxury Tax, Octroi, Entertainment Tax, Taxes on Advertisements, Taxes on Lottery/Betting/Gambling, State cesses on goods |
- Kept out: five petroleum products are out of GST for the time being; State governments continue to levy VAT on alcoholic liquor for human consumption; tobacco attracts both GST and Central Excise Duty
- Categories (rates): the book gives 6 standard rates: 0%, 3%, 5%, 12%, 18% and 28%
- Constitutional basis: the 101st Constitution Amendment Act received the President’s assent on 8 September 2016; it introduced Article 246A, empowering Parliament and the State Legislatures to make laws on GST; then the CGST, UTGST and SGST Acts were enacted
- Benefits: fewer taxes; free movement of goods and services and a common market; lower cost of business and of cascading; Indian products more competitive at home and abroad; GDP expected to rise by about 2%; registration, returns and payments online at www.gst.gov.in; wider tax base, more transparency, less human interface between taxpayer and government, greater ease of doing business
12 Key Formulas
| Measure | Formula |
|---|---|
| Revenue deficit | Revenue expenditure − Revenue receipts |
| Fiscal deficit | Total expenditure − (Revenue receipts + Non-debt creating capital receipts) = total borrowing |
| Fiscal deficit (relation) | Revenue deficit + Capital expenditure − Non-debt creating capital receipts |
| Primary deficit | Fiscal deficit − Net interest liabilities |
| Government expenditure multiplier | 1 ÷ (1 − c) |
| Tax multiplier | −c ÷ (1 − c) |
| Transfer multiplier | c ÷ (1 − c); with proportional tax c ÷ [1 − c(1 − t)] |
| Balanced budget multiplier | 1 |
| Multiplier with proportional taxes | 1 ÷ [1 − c(1 − t)] |
13 Differences the Exam Asks For
| Basis | Revenue receipts | Capital receipts |
|---|---|---|
| Liability | None (non-redeemable) | May create one (borrowing) |
| Assets | No reduction | May reduce them (disinvestment, recovery of loans) |
| Examples | Taxes, interest receipts, dividends, fees, grants | Borrowing, recovery of loans, disinvestment |
| Basis | Revenue deficit | Fiscal deficit |
|---|---|---|
| Formula | Revenue expenditure − Revenue receipts | Total expenditure − (Revenue receipts + Non-debt capital receipts) |
| Shows | Borrowing for consumption, government dissaving | Total borrowing requirement from all sources |
| Relation | The revenue deficit is a part of the fiscal deficit | |
| Basis | Automatic stabiliser | Discretionary fiscal policy |
|---|---|---|
| Works | Automatically, with no decision | Through deliberate government action |
| Examples | Proportional income tax, welfare transfers | Raising G when investment falls |
| Limit | Removes only part of the fluctuation | Needed for the rest |
- Budget = estimated receipts and expenditure for the financial year (1 April to 31 March); Article 112; revenue budget + capital budget
- Three objectives: allocation (public goods), redistribution (taxes, transfers), stabilisation (demand)
- Public goods are non-rivalrous and non-excludable; the free-rider problem
- Test: liability created or asset reduced = capital receipt; asset created or liability reduced = capital expenditure
- Interest received or paid is revenue; loan principal given, recovered or repaid is capital
- RD = RE − RR; FD = TE − (RR + non-debt capital receipts) = borrowing; PD = FD − interest
- 2024-25: RD 2.6%, FD 5.6%, PD 2.0% of GDP
- Multipliers: G 1/(1 − c), tax −c/(1 − c), transfer c/(1 − c), balanced budget 1, proportional tax 1/[1 − c(1 − t)]
- Ricardian equivalence; debt is burdensome if it reduces future growth; deficits need not be inflationary
- FRBMA 2003: FD 3%, RD eliminated; GST 1 July 2017, 6 rates, ITC
- Can I classify any receipt or expenditure as revenue or capital, with the reason?
- Can I work out all three deficits from data, step by step?
- Can I find an unknown item such as tax revenue from the fiscal-deficit identity?
- Can I find equilibrium income with the government and all four multipliers?